There's No Such Thing as a FINTRAC Fee. So Why Did She Pay One?
Is the FINTRAC registration fee real? Here's how the scam works, and what happened when a Canadian was told to pay one.
Is the FINTRAC Registration Fee Real?
FINTRAC does not charge private individuals a fee to release their own funds. There is no such thing as a "FINTRAC registration fee," a "compliance release fee," or a "crypto withdrawal tax" paid to a regulator. If you were told your account or wallet is frozen until you pay one, it is a fraud, and no legitimate financial intelligence unit anywhere in the world works this way.
We saw this play out in full this summer, with a Canadian who lost roughly $83,000 to exactly this scam. Her bank caught it in progress and warned her outright. She sent the money anyway, because by the time she made that call, she had already been prepared to.
The bank warned her it was a scam but she asked them to send the money anyway.
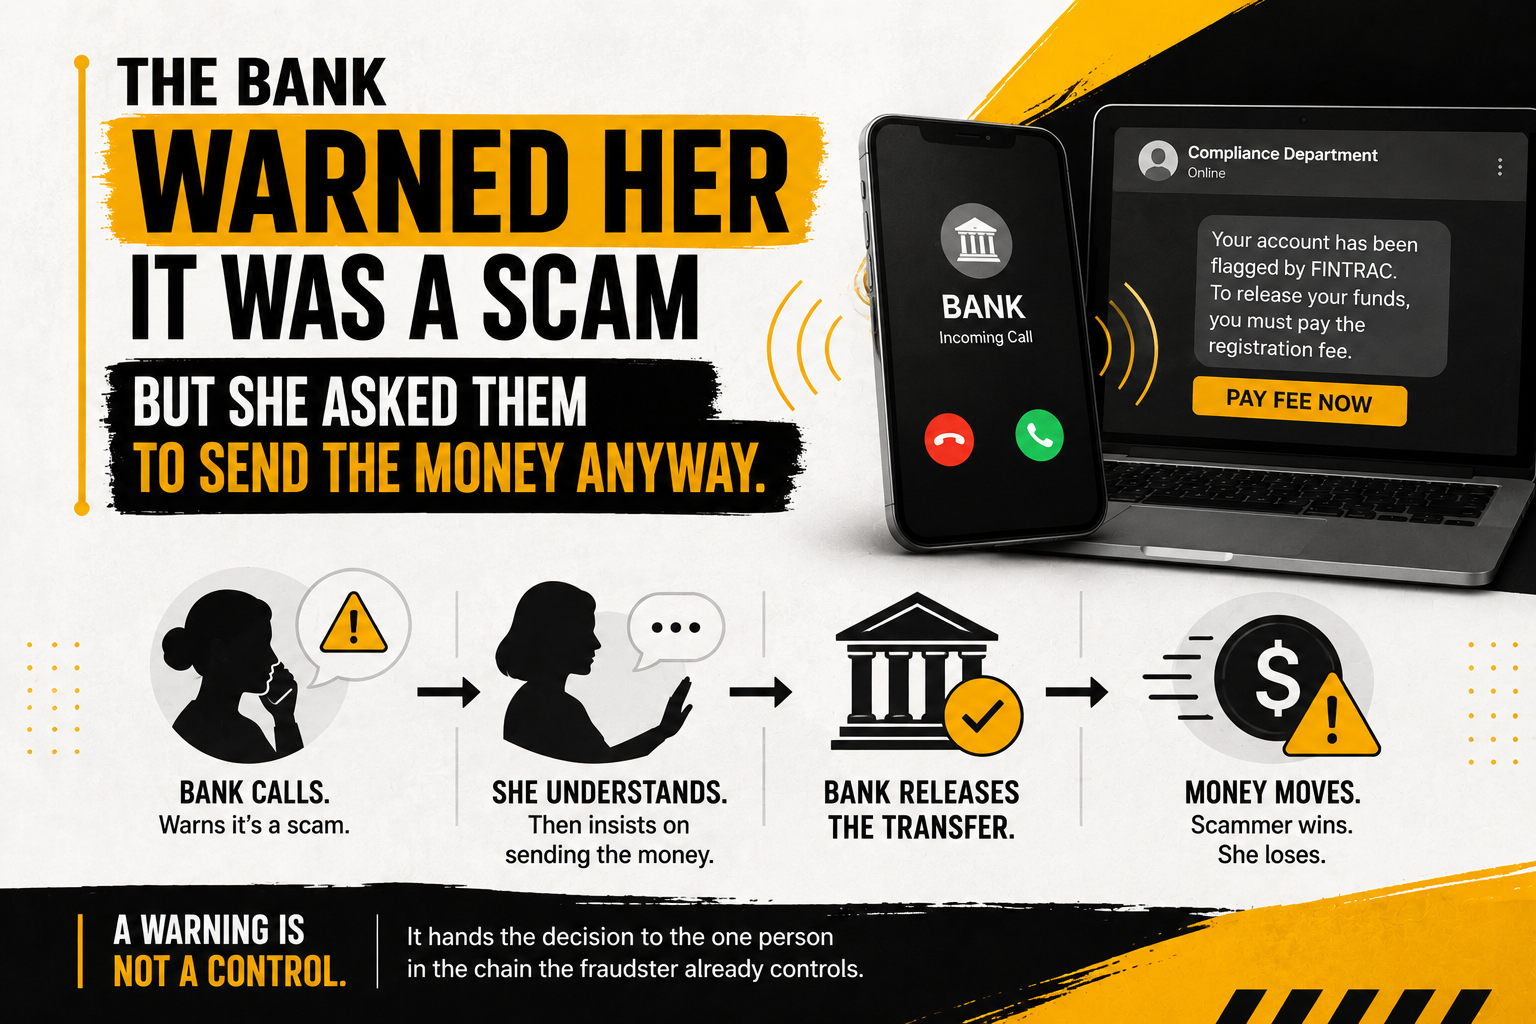
Before the money left her account, her bank called her.
They asked where it was going. She said she was investing in cryptocurrency. The banker told her that offers like this are almost always a scam and that she should not go through with it. She said she understood. Then she asked them to release the transfer anyway and so they did.
A warning hands the decision to the one person in the chain the fraudster already controls.
How did it happen?
A first-ever cryptocurrency purchase, a few thousand dollars, made through a regulated Canadian platform. Her balance appeared to grow. When she tried to withdraw it, she could not work out how, so she searched online for help.
The search was the funnel. A man presenting himself as a lawyer found her there and offered to recover her funds. Recovery, he told her, required her to send more. So she did, in escalating transfers, to a new counterparty her account had never sent money to before. The funds moved out of her bank through one of the largest cryptocurrency exchanges in the world, and into a self-custody wallet opened in her own name.
The money passed through the entire regulated perimeter and arrived intact on the other side.
Her real loss came to roughly $83,000: about $2,500 as the original investment, then about $80,000 sent on the fake lawyer's instruction. The balance she watched grow into six figures on her screen was just a number the fraudsters showed her.
She had already been approached by a second outfit offering to recover her funds for an upfront fee before she found us.
Recovery scams are a separate industry that finds victims at their lowest point, and in this case the step that was framed as recovery took far more money than the original transaction did.
Compliance became the lure
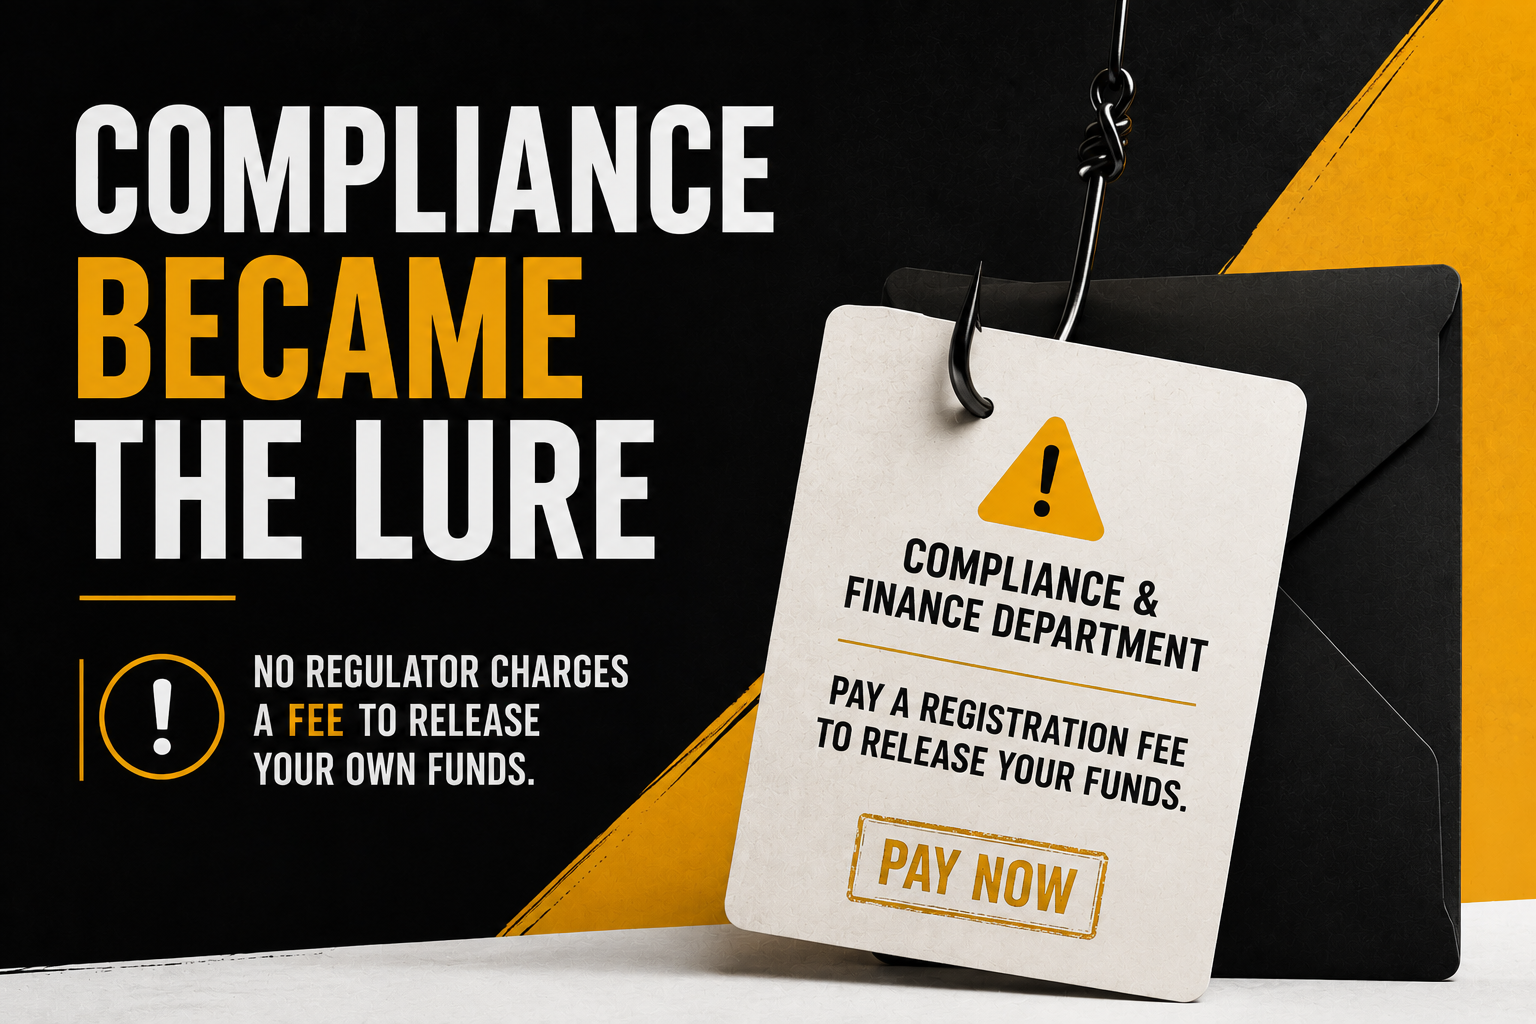
After the transfer, she was told her funds had been frozen. The message appeared to come from a "compliance and finance department" and named a condition for release: a registration fee, payable to FINTRAC.
FINTRAC does not collect fees from private individuals. There is no registration fee for a person to move their own money, and there never has been. No financial intelligence unit anywhere works that way. It is checkable in under a minute, and it is the single strongest fact in this story.
For a decade, the public has been asked for identity documents, source-of-funds explanations, and verification steps by institutions they are not in a position to question. Compliance has trained people to expect that moving money involves official obstacles imposed by bodies they have never heard of. A fraudster who says "the regulator requires a fee" is speaking a language his victim has already been taught to obey.
If you have searched anything like "is the FINTRAC fee real" or "crypto withdrawal blocked compliance," this is your answer: no regulator, financial intelligence unit, or government body anywhere charges a private individual a fee to release their own funds. Anyone asking for one is committing a fraud. There is no exception to that.
What should change?
Customer insistence should be treated as a risk signal. Current practice tends to document the warning and defer to the customer's instruction but insistence is not evidence that the customer understands.
For families, the most dangerous moment is the search for help that comes after.
For everyone: no regulator, financial intelligence unit, or government body charges a private individual a fee to release their own funds. Anyone who tells you otherwise is committing a fraud.
AMLI NOTES:
-
No regulator anywhere charges a private individual a fee to release their own money. If you are asked for one, it is a fraud.
-
Recovery offers that appear after a fraud, especially ones that ask for an upfront fee, are frequently a second, separate scam.
-
Funds can pass through a bank, a regulated crypto platform, and a major exchange, and still end up gone. Regulation of the pipes does not guarantee protection of the person.
Frequently asked questions
Is the FINTRAC registration fee real?
No. FINTRAC does not collect fees, deposits, or "registration" payments from private individuals to release their own funds. It never has. If you have been asked to pay one, whether by email, text, or a message inside a wallet app, it is a scam.
What is a FINTRAC registration fee scam?
It is a fraud that impersonates FINTRAC, Canada's financial intelligence unit, after a person's crypto or bank funds have already been moved or frozen by other means. The victim is told their money is being held by a "compliance department" and that a percentage fee, often framed as a FINTRAC registration or release fee, must be paid before the funds can be returned. No such fee exists at FINTRAC or any equivalent regulator.
How do crypto recovery scams work in Canada?
After an initial fraud, victims often search online for help getting their money back. That search is frequently intercepted by a second scam: someone posing as a lawyer, recovery agent, or compliance officer who offers to retrieve the lost funds in exchange for an upfront payment. This second stage can cost the victim significantly more than the original fraud did.
What does a fake compliance fee crypto scam look like?
Typically it starts with a small, legitimate-looking crypto investment. The victim's balance appears to grow. When they try to withdraw, they cannot, and are told by a "compliance" or "finance" department that a fee must be paid first. The fee demand is fraudulent.
My crypto withdrawal is blocked by "compliance." What should I do?
Do not pay any fee to unblock it. Contact your bank's fraud department directly using the number on your card or statement. Report it to your local police and to Canada's Anti-Fraud Centre. If a specific exchange or platform is involved, contact their official support channel directly, not a link or contact provided by the person claiming to help you.
We're not sharing this to embarrass her. She did exactly what the scam was built to make anyone do, and she was the one who reached out for help the moment something felt wrong enough to question. The only reason we're telling it is so the next person gets to the question "is this fee real" before they've sent the money.
How AML Incubator Supports Crypto Platforms and Exchanges
AML Incubator works with crypto platforms, exchanges, and fintechs to build compliance programs that catch fraud like this before it moves through the regulated perimeter, not after.
- CAMLO / MLRO Outsourcing and Compliance Officer Placement
- Compliance Program Design
- Independent Effectiveness Reviews
- AMLI Labs: Compliance Support for Early-Stage Crypto Startups
If your fraud controls still treat customer insistence as a green light instead of a red flag, this is the moment to change that, before it costs someone their savings and costs you an examination.